Q2 2023 – Quarterly Report Commentary
Hosking Partners is a London boutique founded in 2013 by Jeremy Hosking, a portfolio manager at Marathon Asset Management for over 25 years. It runs a single global equity strategy built on the capital-cycle, supply-side approach — contrarian, long-term, and unusually diversified (350+ holdings) under a multi-counsellor model, managing around $5.5bn.
In plain words
This report covers Hosking Partners' Q2 2023 performance and views. The fund sees a shift from 'virtual world' tech stocks to 'physical world' sectors like banks and energy, but short-term pain is real, so they're cautiously optimistic. Key moves: they underweighted Microsoft, Nvidia, Apple, Meta, and Tesla, which hurt returns as these stocks surged 18-52%. They added to offshore drilling positions, citing supply constraints (60% of floating rigs scrapped, no new orders in a decade). They also hold Japanese value stocks, benefiting from government-led capital efficiency reforms and record foreign inflows of $70 billion.
At a Glance
The author believes the market is rotating from the "virtual world" to the "physical world," but short-term pain is evident, with a stance of [cautiously optimistic].
- The portfolio underperformed the broader market this quarter, with roughly half of the shortfall attributable to underweight positions in five "virtual world" stocks—Microsoft, Nvidia, Apple, Meta, and Tesla (which together account for about 11.3% of the MSCI ACWI and posted gains of 18-52% this quarter).
- Approximately 75% of the portfolio is tilted toward the "physical world" (banks, mining, energy, etc.), with short-term economic sensitivity weighing on performance.
- The Japan allocation (about 10%) benefited from capital efficiency reforms, with net foreign inflows of $70 billion this quarter—the fastest pace since 2012.
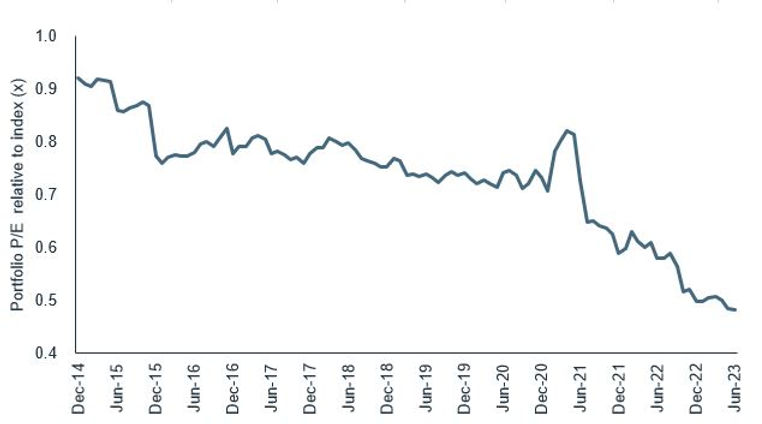
- The portfolio's P/E ratio relative to the market fell from 0.95x to 0.5x, with continued accumulation of offshore drilling positions (industry supply constrained: 60% of floating rigs scrapped, no new orders in nearly a decade).
Underperformed This Quarter; Underweight in Five "Virtual World" Stocks Was the Main Cause
Performance Comparison: The portfolio lagged this quarter, with roughly half of the underperformance attributable to underweight positions in five "virtual world" stocks—Microsoft, Nvidia, Apple, Meta, and Tesla—which together account for about 11.3% of the MSCI ACWI and posted gains of 18-52% this quarter. The Nasdaq rose 15.2% in USD terms this quarter and 38.7% in the first half of the year; the U.S. contributed approximately 85% of MSCI ACWI returns, led by large-cap tech stocks. About 75% of the portfolio is tilted toward the "physical world" (banks, mining, energy, etc.), and short-term economic sensitivity weighed on performance.
U.S. Banking Crisis Accelerated Trends; Large Banks Benefited
The report argues that the U.S. banking crisis in late March was an event that "accelerated trends rather than changed direction." Large banks benefited from deposit inflows from smaller institutions, and well-capitalized "winners" performed strongly this quarter. Risk Note: Whether Silicon Valley Bank's collapse is an isolated incident or a precursor to broader industry problems depends on the depth of the predicted recession. Unlike the global financial crisis, the current risks lie in off-balance-sheet items and non-traditional lending/private equity; how these credits flow back into the banking system is a key focus.
Japan Positions Benefited from Capital Efficiency Reforms; Foreign Inflows Hit Record
The portfolio's roughly 10% Japan allocation is dominated by value-oriented companies. The Nikkei 225 rose 18.4% this quarter (27.2% in the first half), while the Topix gained 21.0% over the same period. The Tokyo Stock Exchange required listed companies to "urgently" assess their cost of capital and address price-to-book issues, with AGM proposals up 18% year-on-year this quarter. The author stated, "Cajoled by the government and regulators, minority shareholders are finding their voice." Foreign net inflows reached $70 billion this quarter, the fastest pace since Abe's second election in 2012. The author believes this is a "long game," but not a solitary effort.
Portfolio Valuation Discount Widened; Continued Accumulation of Offshore Drilling
The portfolio's P/E ratio relative to the market has fallen from 0.95x to 0.5x over the past decade, reflecting a strategy of consistently selling expensive U.S. stocks and buying cheaper companies. This quarter, the portfolio continued to increase its offshore drilling positions. The industry has experienced a decade of underinvestment: 60% of floating rigs have been scrapped, consolidation has reduced the field to just seven major publicly listed players, nearly all have undergone Chapter 11 restructuring, and after $50 billion in enterprise value was destroyed from 2014 to 2019, no new orders have been placed for nearly a decade. The author believes supply constraints are a strong tailwind for day rates and profitability.
A Tough First Half, but Discipline in Value and Capital Cycles Remains
Outlook: The author acknowledges that the first half was challenging for many active funds (including Hosking), given the portfolio's low valuation, diversification, and deviation from large-cap U.S. stocks. However, the report emphasizes that "frustrations are tempered by opportunities" and will continue to seek opportunities in unloved small- and mid-cap stocks through the lens of capital cycles.
Position Moves (Mentioned in This Chapter)
| Position | Action | Logic & Data |
|---|---|---|
| Microsoft | Underweight (not explicitly stated) | Up 18-52% this quarter; underweight contributed roughly half of relative underperformance |
| Nvidia | Underweight (not explicitly stated) | Same as above |
| Apple | Underweight (not explicitly stated) | Same as above |
| Meta | Underweight (not explicitly stated) | Same as above |
| Tesla | Underweight (not explicitly stated) | Same as above |
| Large U.S. Banks | Hold & Observe | Benefiting from deposit inflows from smaller banks; strong performance this quarter |
| Japanese Value Companies | Hold & Observe | Portfolio weight ~10%; benefiting from capital efficiency reforms, with multiple firms raising capital return targets |
| Offshore Drilling Companies | Add to Position | Industry supply constrained (60% of floaters scrapped, nearly no new orders in the past decade); day rates benefiting |
Position Moves
| Ticker | Direction | Author's One-Sentence View | Key Data |
|---|---|---|---|
| Offshore Drilling Companies | Increased Position | Industry supply constraints are a strong tailwind for day rates and profitability | 60% of floaters scrapped, no new orders in nearly a decade |
| Microsoft | Not Disclosed | Underweight led to relative underperformance this quarter | This quarter's gain 18-52% |
| Nvidia | Not Disclosed | Underweight led to relative underperformance this quarter | This quarter's gain 18-52% |
| Apple | Not Disclosed | Underweight led to relative underperformance this quarter | This quarter's gain 18-52% |
| Meta | Not Disclosed | Underweight led to relative underperformance this quarter | This quarter's gain 18-52% |
| Tesla | Not Disclosed | Underweight led to relative underperformance this quarter | This quarter's gain 18-52% |
| Large U.S. Banks | Hold & Observe | Benefiting from deposit share inflows from smaller banks, performed strongly this quarter | Silicon Valley Bank crisis accelerated the trend |
| Japanese Value Companies | Hold & Observe | Benefiting from capital efficiency reforms, minority shareholders are making their voices heard | Portfolio ~10% position, foreign net inflows of $70 billion |